
- About the Client
- Client’s Challenges
- 1. Rule-based checks missed relationships between fraud indicators
- 2. Legitimate claims generated too many fraud alerts
- 3. Investigators had to manually connect information across records
- 4. The screening process did not rank claims by fraud risk
- 5. Investigators lacked clear visibility into why a claim was flagged
- Our Solution
- Implementation Timeline
- Core Capabilities Delivered
- Results and Business Impact
- Client Testimonial
- From Rule-Based Screening to More Accurate Insurance Fraud Detection
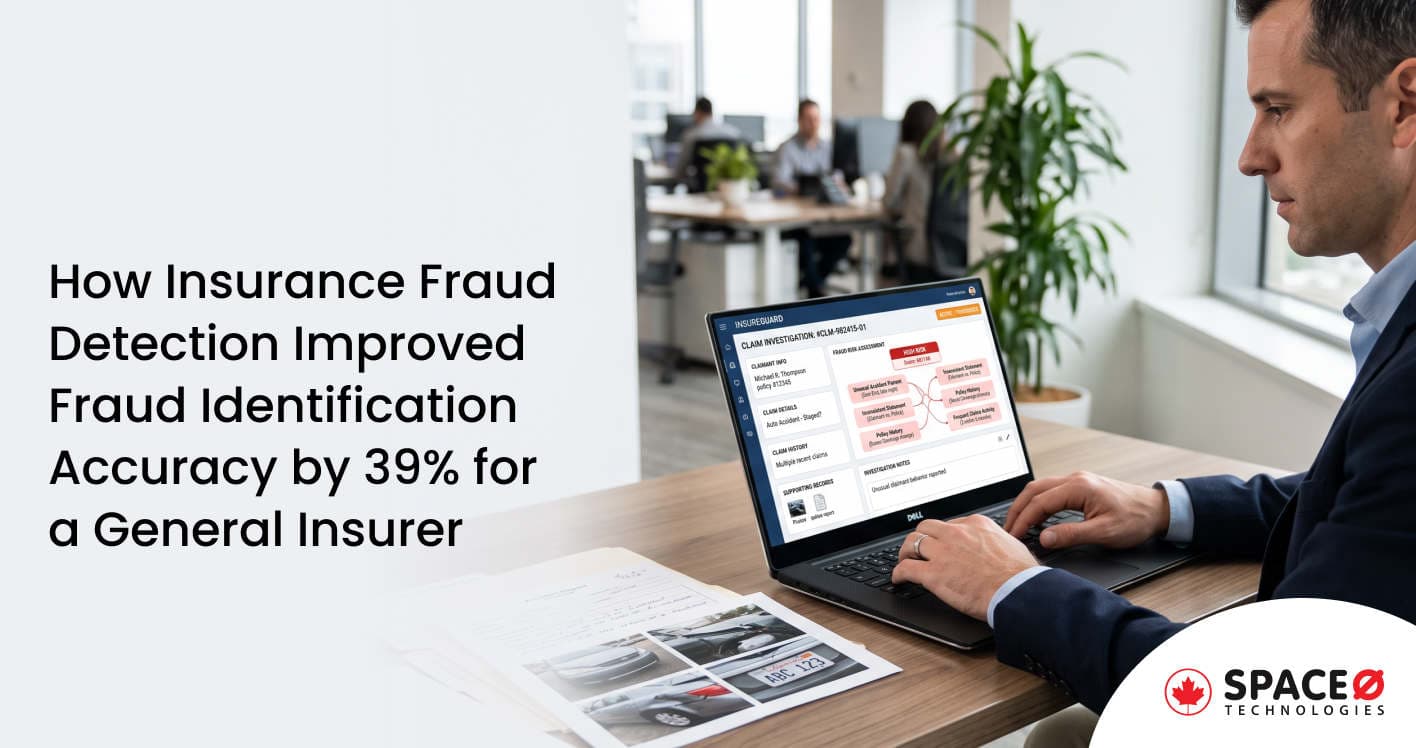
How Insurance Fraud Detection Improved Fraud Identification Accuracy by 39% for a General Insurer
 Last Updated: November, 17 2026
| Industry | Insurance |
|---|---|
| Timeline | 6 Months |
| Platforms | Claims Management Platform, Fraud Detection System |
| Services Provided | Insurance Software Development, Insurance Fraud Detection Software Development |
A mid-sized general insurance provider in Canada processed around 280,000 claims annually across its auto, home, and commercial insurance lines. Its claims team used predefined fraud rules and manual investigation to identify claims that required closer review.
As claim volumes grew, the insurer found it increasingly difficult to distinguish genuinely suspicious claims from legitimate ones. Investigators spent time reviewing false alerts, while some suspicious patterns remained difficult to identify when they appeared across different claims or customer records.
The insurer needed a more consistent way to screen claims, identify relevant fraud indicators, and prioritize cases for investigation without adding more manual work to its claims operation.
Space-O Canada developed an insurance fraud detection solution that analyzed claims against defined fraud indicators and risk patterns. The system generated risk-based alerts for claims requiring further investigation and gave investigators a structured view of the factors contributing to each alert.
About the Client
The client is a mid-sized general insurance provider based in Canada, offering auto, home, and commercial insurance products to individuals and businesses.
The insurer processed around 280,000 claims annually through a claims management environment that brought together policyholder information, claim details, supporting documents, adjuster assessments, and payment records.
Its fraud investigation team used a combination of predefined rules, claims history, and manual reviews to identify potentially suspicious claims. The approach worked for straightforward fraud indicators but became less effective when suspicious activity involved multiple data points or appeared similar to legitimate claims.
As the insurer expanded its digital claims processes, it needed to improve how it identified potentially fraudulent claims without sending a larger volume of legitimate claims to investigators. The goal was to introduce a more consistent fraud screening process while keeping final investigation and claim decisions with the insurer’s existing teams.
Client’s Challenges
The insurer’s existing fraud screening process could identify common red flags, but it struggled to evaluate multiple fraud indicators together. As a result, investigators had to perform additional checks to determine which claims showed genuine signs of suspicious activity.
1. Rule-based checks missed relationships between fraud indicators
The insurer used predefined rules to flag claims based on individual indicators such as unusual claim amounts, claim frequency, or changes in policy information. These checks worked well for known fraud scenarios but had limited ability to connect several weaker indicators that became significant when viewed together.
For example, a claim might not trigger an alert based on its value or filing date alone. However, when combined with previous claims, policy changes, and other claim details, the activity could warrant further investigation. The existing rules did not consistently surface these relationships, which limited the accuracy of the initial fraud screening.
2. Legitimate claims generated too many fraud alerts
Some rules were intentionally broad to avoid missing potentially fraudulent claims. This also meant that legitimate claims could trigger alerts when they matched one or more suspicious conditions.
Investigators had to review the underlying claim information to determine whether an alert represented a genuine fraud concern or a legitimate claim that happened to meet a predefined rule. This consumed investigation capacity and made it harder for the team to focus on claims with stronger fraud indicators.
3. Investigators had to manually connect information across records
Identifying potential fraud often required investigators to compare information from the current claim with the claimant’s policy details, previous claims, and related records. The existing process did not provide a consolidated view of these relationships.
Investigators therefore spent time moving between records and comparing information before they could determine whether a claim showed a recurring or unusual pattern. This manual analysis also made the initial assessment dependent on how quickly and consistently each investigator could identify relevant connections.
4. The screening process did not rank claims by fraud risk
The existing alerts indicated that a claim required attention but provided limited differentiation between lower-risk and higher-risk cases. Investigators therefore had to assess the available claim information before deciding which cases required immediate attention.
As the number of alerts increased, the lack of consistent risk-based prioritization made it difficult to direct investigation resources toward the claims with the strongest combination of fraud indicators.
5. Investigators lacked clear visibility into why a claim was flagged
A fraud alert did not always provide investigators with a consolidated explanation of the indicators that contributed to the alert. Investigators had to review the claim and supporting records themselves to establish why the activity appeared unusual.
This increased the time required for the initial assessment and made it harder to maintain a consistent approach to fraud identification. The insurer needed a screening process that could surface relevant fraud indicators and provide investigators with enough context to evaluate each case efficiently.
Our Solution
Space-O Canada integrated an insurance fraud detection layer into the insurer’s existing claims workflow. The solution brought together claims and policy data, evaluated multiple fraud indicators, and assigned risk levels to help investigators prioritize claims requiring further investigation.
1. Bringing relevant claims information together
We connected the fraud detection layer with the insurer’s existing claims and policy data. The solution brought together information such as current claim details, previous claims, policy history, and other relevant claim attributes during the screening process.
This reduced the need for investigators to manually move between records to establish whether a current claim shared characteristics with previous activity. It also gave the screening process a broader set of information from which to identify potential fraud indicators.
2. Evaluating combinations of fraud indicators
We configured the screening logic to evaluate multiple indicators together rather than triggering an alert whenever a single rule was matched.
The solution could assess combinations of factors such as unusual claim characteristics, previous claim activity, repeated patterns, and relevant policy changes. This helped distinguish isolated rule matches from combinations of indicators that presented a stronger reason for investigation.
3. Reducing low-value fraud alerts through risk assessment
The solution assigned a risk level based on the combination and significance of the indicators identified during screening. Claims showing stronger combinations of indicators received higher investigation priority, while lower-risk matches could continue through the standard claims workflow.
This helped reduce the number of legitimate claims treated as equally important fraud alerts. Investigators could focus their attention on higher-risk cases while lower-risk claims continued through the normal claims workflow.
4. Showing investigators why a claim was flagged
We provided investigators with visibility into the fraud indicators associated with each flagged claim. Instead of receiving an alert without sufficient context, investigators could see the factors that contributed to the claim’s risk assessment.
The additional context helped investigators understand why a claim had been flagged and begin their review with relevant information already identified. This supported a more consistent approach to the initial assessment of suspicious claims.
5. Prioritizing claims for investigation
The solution organized flagged claims according to their assessed fraud risk, giving investigators a structured queue for further review.
Investigators could therefore prioritize claims with stronger combinations of fraud indicators instead of spending similar amounts of time on every alert. The workflow preserved human judgment for the final investigation while using automated screening to direct that judgment where it was most needed.
6. Automating the initial fraud screening process
The fraud detection layer automatically evaluated claims as they entered the claims workflow. Claims with no significant fraud indicators could continue through the standard process, while claims meeting stronger risk conditions could be routed for investigation.
This allowed the insurer to scale its initial fraud screening without requiring investigators to manually assess every claim. By combining automated screening with investigator-led review, the insurer improved the consistency of fraud identification while keeping final decisions within the existing claims investigation process.
Implementation Timeline
Space-O Canada implemented the insurance fraud detection solution over six months, moving from claims-data assessment to controlled production rollout.
Phase 1: Claims and fraud workflow assessment (Weeks 1–4)
Our solution team worked with the insurer’s claims and fraud investigation teams to understand how claims were screened, how fraud alerts were generated, and how investigators reviewed flagged cases.
We mapped the existing fraud rules and identified the claim and policy information available for screening. The team also reviewed previously investigated claims to understand which indicators had been useful in identifying suspicious activity and where the existing rules generated unnecessary alerts.
Phase 2: Fraud screening and risk logic development (Weeks 5–12)
We connected the fraud detection layer with the relevant claims and policy data and configured screening logic around the fraud indicators identified during the assessment.
Instead of treating every rule match as an equal alert, the solution evaluated combinations of indicators and assigned risk levels based on the overall pattern. The team also configured the system to retain the indicators contributing to each risk assessment, giving investigators context when reviewing flagged claims.
Phase 3: Historical claim validation and workflow testing (Weeks 13–20)
The team tested the detection logic against previously processed claims, including cases that had been investigated and cleared or identified as potentially fraudulent. This allowed the insurer’s fraud team to compare system-generated risk assessments with the outcomes of earlier investigations.
The team refined the indicators and risk thresholds where the system produced unnecessary alerts or failed to give sufficient priority to stronger fraud patterns. Testing also covered incomplete claim information, duplicate records, and the transfer of high-risk cases into the investigator workflow.
Phase 4: Controlled production rollout and optimization (Weeks 21–24)
The solution was introduced into the insurer’s live claims workflow through a controlled rollout. Investigators reviewed the flagged claims and provided feedback on the relevance of the indicators, risk classifications, and information presented with each alert.
Based on this feedback, the team fine-tuned the screening logic and risk thresholds before completing the production rollout. The insurer then measured fraud identification performance against its previous screening process, resulting in a 39% improvement in fraud identification accuracy.
Core Capabilities Delivered
The solution improved how the insurer screened claims and directed potential fraud cases to investigators. It combined relevant claim information, fraud indicators, risk assessment, and investigator review within the existing claims workflow.
Fraud detection capabilities
1. Multi-indicator fraud screening
The solution evaluated multiple claim and policy indicators together to identify combinations of less obvious signals that warranted further review.
2. Claims and policy data analysis
The fraud detection layer considered relevant information from the current claim, previous claims, and policy records during screening. This helped surface recurring activity and relationships that investigators previously had to identify by comparing records manually.
3. Risk-based claim assessment
The solution assigned a risk level based on the combination and significance of the indicators identified during screening. This helped separate stronger fraud signals from lower-risk matches and gave investigators a more consistent basis for prioritizing cases.
Investigator capabilities
1. Alert-level fraud indicators
Flagged claims displayed the indicators that contributed to their risk assessment. Investigators could therefore see what had triggered the alert before reviewing the claim in greater detail.
2. Prioritized investigation queue
The system organized flagged claims according to their risk level, allowing investigators to focus first on cases with stronger combinations of fraud indicators rather than reviewing alerts in an undifferentiated queue.
3. Consolidated claim context
Investigators could access relevant claim and policy information alongside the fraud indicators identified by the screening process. This reduced the need to switch between records during the initial assessment of a flagged claim.
Operational capabilities
1. Automated initial screening
The solution screened incoming claims against the configured fraud indicators before sending potential cases to the investigation workflow. Claims without significant indicators could continue through the standard process, while higher-risk claims were referred for further review.
2. Fraud rule and threshold management
The insurer could adjust fraud indicators and risk thresholds as its investigation team identified changes in claim patterns or refined its screening requirements. This allowed the screening process to evolve without changing the underlying claims workflow.
3. Screening performance monitoring
The insurer could review screening outcomes and investigator feedback to identify alerts that required further refinement. This provided a basis for adjusting fraud indicators and risk thresholds as the insurer continued to use the system in production.
Results and Business Impact
The insurer measured the new fraud screening process against its previous approach after the solution had been optimized in production. The results showed that the system helped investigators identify potentially fraudulent claims more accurately while reducing unnecessary manual reviews.
| Metric | Before | After | Impact |
|---|---|---|---|
| Fraud identification accuracy | 62.3% | 86.6% | 39% relative improvement |
| Claims requiring manual fraud review | 8.7% | 6.4% | 26% reduction |
| Claims screened automatically | 38% | 89% | 51 percentage-point increase |
- More accurate fraud identification
Fraud identification accuracy increased from 62.3% to 86.6%, representing a 39% relative improvement. The new screening process evaluated multiple claim and policy indicators together rather than relying primarily on individual rule matches. This gave investigators more context when reviewing claims that required further investigation. - Fewer claims requiring manual fraud review
The proportion of claims requiring manual fraud review decreased from 8.7% to 6.4%, a 26% relative reduction. Risk-based screening separated lower-risk matches from claims showing stronger combinations of fraud indicators. This allowed investigators to focus their review capacity on claims that warranted further investigation. - Broader automated screening coverage
Automated screening increased from 38% to 89% of claims, allowing the insurer to apply its fraud detection process more consistently across incoming claims. Investigators remained responsible for reviewing flagged cases and making fraud-related decisions, while the automated screening layer handled the initial assessment and prioritization. - Improved investigator efficiency
Investigators received risk levels and the indicators behind each alert before beginning a detailed review. Instead of manually comparing multiple records to understand why a claim appeared unusual, they could start with the relevant information already surfaced by the detection system. This provided a more consistent starting point for investigation and supported broader fraud screening without increasing the initial manual screening workload at the same rate as claim volumes.
Client Testimonial
“The biggest improvement was not simply generating more fraud alerts. The new screening process helped our investigators understand which claims needed attention and why. We now have a more consistent way to identify suspicious claims without increasing the manual workload across our claims operation.”
— Director of Claims Operations | General Insurance Provider
From Rule-Based Screening to More Accurate Insurance Fraud Detection
Insurance fraud detection becomes harder when isolated rules and manual reviews cannot connect patterns across claims and policy records. Space-O Canada helps insurers automate initial fraud screening, evaluate multiple indicators, and prioritize claims for investigator review.
Space-O Canada helps insurers strengthen fraud detection by connecting relevant claims data, evaluating multiple fraud indicators, and prioritizing higher-risk claims for investigation. The approach supports existing claims operations without replacing the investigators responsible for making final fraud decisions.
If your existing fraud screening process generates too many alerts or makes it difficult to prioritize suspicious claims, talk to our insurance software development team about building a more consistent fraud detection workflow.


Related Case Studies
View All Case Studies
Let’s Discuss Your Idea
Share your idea with our fintech development team and get a practical breakdown of what you need to build, integrate, secure, and launch it.
 Your project is covered by an NDAYour information stays secure and confidential




What our clients say


When we set out to build our Estate Tax Planning Tool, we needed a development partner we could trust with something this complex and consequential. Space-O Canada brought the technical expertise and attention to detail needed to handle intricate tax calculations and edge cases. They communicated clearly, delivered on time without cutting corners, and built a product we trust completely.
 Ed Chetan EdwinFounder, CharityCalc
We partnered with Space-O Canada to build a fintech platform that could support secure transactions, third-party integrations, and future scalability. Their team understood our business requirements from the beginning and delivered a well-architected solution without unnecessary complexity. Communication was consistent, milestones were met on time, and every challenge was handled proactively.
 Michael CarterCo-Founder, Digital Payments Platform
The fintech app came out exactly the way I pictured in terms of functionality. I will refer future UI/UX clients to their team. During the testing phase of the app, it performed according to the initial designs in terms of functionality. Their team was dedicated to creating the best version of the app and provided their own ideas to improve it.
 Amanda LewisProduct Manager, Lending Platform
Our banking modernization project involved complex integrations and strict security requirements, and Space-O Canada handled both with confidence. They developed a reliable banking platform that improved operational efficiency while maintaining a smooth customer experience. Their structured development process and clear communication kept the project on track from start to finish.
 Daniel RobertsVP of Technology, Regional Bank
Our legacy insurance system created delays across policy management and claims processing. Space-O Canada developed a centralized platform that streamlined our workflows and improved efficiency across departments. The project was delivered on schedule, and the team’s understanding of insurance technology was evident throughout the engagement.
 Emily FosterOperations Director, Insurance Provider
Developing a trading platform requires speed, reliability, and technical precision. Space-O Canada delivered a solution that performs exceptionally well while supporting real-time market data and intuitive trading workflows. Their project management was excellent, and the team remained responsive throughout every stage of development.
 Ethan MorganChief Product Officer, Investment Platform
The fintech app was successfully launched, and users loved its sleek design and features. Space-O Technologies worked in an organized and collaborative manner, allowing them to achieve quality results. They also took the time to deeply understand the project. They were very organized and had a good track record.
 David WilsonFounder, Personal Finance App